Managing money across borders usually sounds more complicated than it should. Común caught my attention because it brings everyday payments, transfers to Latin America, and a Visa debit card into one finance app rather than making me jump between several services. After using it as a practical money tool instead of treating it like something to explore once and forget, I found that its real test is not the first transfer. The important question is whether it remains useful when payday routines, family support, card spending, and account maintenance become ordinary habits.
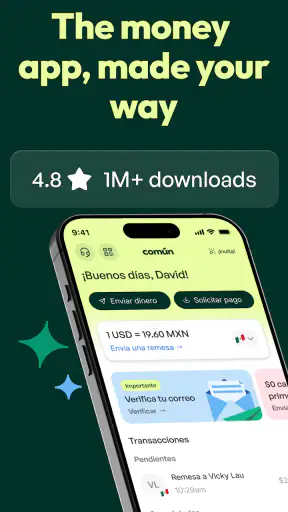
Común is a free finance app from Comun for users aged Everyone, and it runs on Android and iOS devices with operating system version 10 or later. It has built a strong early reputation, with a 4.8 average from around 22 thousand ratings, while its install count has passed 500 thousand. Those figures suggest that the basic idea is resonating, but they do not replace the more personal question: does this fit the way you actually move and spend money?
What Común feels like during the first week
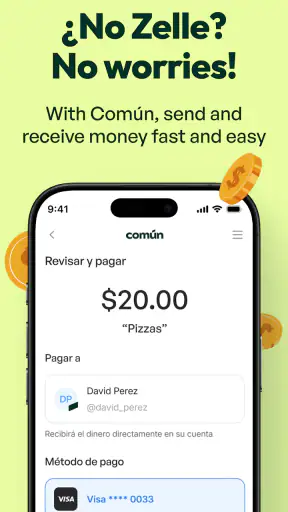
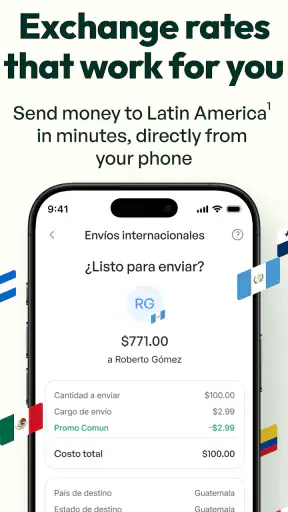
The first-week appeal comes from the app’s focused purpose. Instead of presenting itself as a general-purpose financial dashboard packed with unrelated tools, Común is centered on sending money to people and countries connected to Latin America, paying others, and using a Visa debit card. That makes the initial setup feel easier to understand. I could approach it with a specific job in mind: sending support to family, paying someone, or keeping a card available for regular purchases.
The combination of a money account and a physical or digital spending route is especially appealing for someone who dislikes separating transfers from card use. In a typical arrangement, I might need one service for moving money internationally, another bank for daily spending, and a separate card app for transaction checks. Común’s attraction is the possibility of keeping those activities closer together. That does not automatically make it the best financial home for everyone, but it reduces the mental switching that often makes cross-border money management tiring.
A realistic example is a user who receives income in the United States and regularly helps relatives in Latin America. During the first week, the value is easy to see: the app can become the place to initiate a family transfer, use a Visa debit card for ordinary purchases, and review the activity afterward. The benefit is not simply speed or novelty. It is the reduction of small decisions about which service to open for each task.
I also like that the app’s audience is broader than people sending large, formal remittances. A person could use it for occasional family support, shared expenses, or payments to someone in their personal network. That makes it more approachable than a service that feels designed only for major international transfers. At the same time, occasional users should not assume that an app designed around recurring money movement eliminates the need to check every transaction carefully.
The Visa debit card gives the product a more concrete place in daily life. A transfer app can be useful once a month and then disappear from memory. A card can create a reason to return to the app during the week. That recurring contact matters because it makes Común easier to evaluate honestly: after the first successful payment, I can see whether the card and account fit naturally into my routine or whether they become another thing to monitor.
Where the first-week experience needs care
The smoothest start depends on knowing your main use case before signing up. If your goal is sending money to Latin America, think about the people and destinations you expect to use most often. If your goal is everyday spending, consider whether you want Común to be a primary card or simply a dedicated card for cross-border needs. Treating it as a focused tool produces a clearer test than trying to make it replace every financial service immediately.
I would also avoid judging the app solely by how quickly the first interaction feels. Financial apps involve real consequences, so I prefer to check the recipient details, transfer destination, and card activity deliberately rather than rushing because the interface seems simple. The best early habit is to verify every payment before confirming it, especially when the app is being used for family support or money that cannot easily be recovered from a mistake.
Another useful approach is to begin with a manageable recurring task. For example, I might use Común for one regular family payment or a limited set of card purchases before moving more activity into it. This reveals whether the app fits my actual rhythm, not just whether it can complete a single transaction. It also makes it easier to notice any friction in keeping records, checking balances, or remembering which expenses belong to which purpose.
Why the value can continue from month to month
The long-term appeal depends on repetition. Común earns a place in my routine when it saves effort every month, not when it merely offers an attractive first impression. For someone with regular connections to Latin America, the central value is having a familiar route for sending money and a connected way to spend. That can be meaningful even if the user does not open the app every day.
One of the strongest use cases is separating cross-border responsibilities from a primary domestic bank account. A user may want a dedicated place for family transfers or international spending so those transactions are easier to recognize. Común can serve that role more clearly than a traditional bank account filled with unrelated bills and subscriptions. This is a practical organizational advantage, particularly for people who need to distinguish support payments from personal spending.
The Visa debit card also affects the monthly calculation. A card that is used for a defined purpose can make budgeting more visible: travel spending, family-related purchases, or money intended for a specific household need can be kept within one recognizable channel. I would not call that a complete budgeting system by itself, but it can make a recurring category easier to follow than when the same expenses are scattered across several accounts.
Compared with a conventional bank, Común feels more specialized. A bank may be better for a broad financial relationship involving savings, loans, local bill payments, and long-established account services. Común is more compelling when the central problem is moving money to Latin America and having a connected debit card. Compared with a single-purpose remittance service, it has a wider everyday role because the card gives the user a reason to keep the app active between transfers.
That comparison also reveals the trade-off. A specialized app may be more convenient for one important task while being less suitable as a complete replacement for a bank. I would keep my expectations narrow and practical: use Común where its cross-border and card functions solve a real problem, rather than assuming that one app must handle savings, credit, investments, and every household payment.
Three habits that make the app more useful
First, I would give every recurring transfer a clear purpose before sending it. “Family support,” “shared rent,” and “emergency help” are different categories even when they go to the same region. Keeping that distinction in my own records makes monthly review easier and prevents the app from becoming a stream of transactions with no context.
Second, I would use the debit card deliberately rather than casually adding it to every payment situation. A dedicated card is most useful when I know why I am using it. Reserving it for cross-border spending or a defined monthly category makes the account easier to reconcile and reduces the chance that it becomes an untracked secondary wallet.
Third, I would schedule a short monthly check rather than waiting for a problem. I would review recent card activity, confirm that transfers went to the intended recipients, and decide whether the app is still serving its original purpose. This is a small maintenance habit, but it is the difference between a helpful financial tool and an account that quietly becomes difficult to understand.
The maintenance burden after the novelty fades
Común is not maintenance-free simply because it combines several money functions. The app may reduce the number of services I use, but it does not remove the responsibility to monitor transactions and keep my financial setup organized. Any card connected to regular spending needs attention, and international transfers deserve more care than a casual tap-and-forget approach.
For me, the maintenance burden is reasonable when the app replaces repeated work. If I am already sending money to Latin America and need a debit card for related spending, one focused app can simplify the routine. If I only make a rare transfer and already have a trusted solution, adding another account, card, and app may create more upkeep than value.
The current version is 2.29.0, which indicates that the product is being maintained as an active app rather than sitting unchanged after launch. I still would not install updates blindly or ignore changes in the way I use it. Financial apps deserve a quick review after major updates: I want to know where familiar actions moved and whether my normal workflow still feels clear.
Account organization is another quiet responsibility. When an app supports both payments and card spending, the transaction history can become more important than the home screen. I would make a habit of checking whether an expense was a card purchase or a transfer, especially when preparing a personal budget. This is a non-obvious strength of a combined app only if the user actually takes advantage of the single place to review activity.
There is also a human maintenance issue: recipient accuracy. Cross-border support is often personal and time-sensitive, so a mistake is more serious than buying the wrong snack with a card. I would slow down for recipient selection, confirm the destination, and avoid sending money while distracted. Común can streamline the process, but convenience should not be confused with permission to skip verification.
Where users may feel fatigue
The first source of fatigue is repetition without a clear record. If I send similar amounts to the same people every month but do not label or document the purpose elsewhere, the app can become difficult to interpret later. That is not necessarily a flaw in Común; it is a reminder that a payment tool is not automatically a personal accounting system.
The second is divided attention between multiple financial services. Común may be a strong fit for cross-border activity, yet many users will still keep a traditional bank, another card, and perhaps a separate savings tool. The app reduces fragmentation only when I assign it a defined role. If I add it without changing my existing habits, I may end up with one more balance and one more card to monitor.
The third is the possibility of expecting the Visa debit card to behave like a complete banking relationship. A debit card is useful for spending, but it does not by itself provide every feature someone might want from a full bank. Users who need broad financial products, extensive local services, or a single institution for every money need may find a conventional bank more comfortable.
There is also a psychological fatigue that comes from using financial tools for family obligations. Regular support payments can feel routine, but they still require planning. I would set a monthly amount in my own budget before opening Común, rather than deciding spontaneously each time. This keeps the app from becoming the place where emotional urgency overrides a realistic spending plan.
People who should probably skip Común are those looking only for a broad investment platform, a full-service bank replacement, or a card with no interest in Latin American transfers. The app’s appeal is specific. It is strongest when sending money and connected card spending are central needs, not when those functions are incidental.
My long-term verdict on Común
After the initial novelty fades, Común still has a credible reason to remain installed. Its lasting value comes from combining two activities that often belong together for its target user: sending money to Latin America and spending through a Visa debit card. The product feels most convincing when it is given a clear job, such as supporting family, handling cross-border expenses, or maintaining a dedicated spending channel.
I would recommend it to someone who wants a focused finance app from Comun and prefers a single routine for payments, international transfers, and card use. The free price makes it easy to try without committing to a paid subscription, and the Everyone age rating keeps the product broadly approachable. Its strong 4.8 average and more than 2.7 thousand written reviews also show that many users have found the concept worthwhile.
My recommendation comes with boundaries. I would not make it my only financial service without first checking whether it covers all of my personal needs. I would also avoid using it casually for every kind of spending, because the app becomes easier to manage when its purpose stays visible. A traditional bank may be the better anchor for someone seeking a broad financial relationship, while a single-purpose transfer service may be enough for a person who rarely needs anything beyond sending money.
The most important test is simple: after a month, does Común remove a repeated inconvenience? If the answer is yes, it can earn lasting space on the phone and in the monthly budget. If it merely duplicates an existing card and transfer service, the extra maintenance may not be justified. In my experience, Común works best as a deliberate cross-border money companion, not as a universal replacement for every financial app.
That is a sensible position for a finance product. I do not need it to do everything; I need it to make an important routine clearer and less scattered. For users whose lives include regular payments to Latin America, the combination of transfers and a debit card gives Común recurring value. For everyone else, the app is worth considering only when that specific need is strong enough to survive beyond the first week.


